
I used to support my own bank. I soon realised they were just like anyone else. Turn down opportunities and pick up illegalities. Seems like the same playbook that I was talking about. They all do the same. Bend to money, will always get tou caught when you have someone who knows where to look, or will sell their data to the highest bidder.
WHEN THE MONEY MOVES, THE QUESTIONS STOP. WHEN THE DAMAGE EMERGES, EVERYBODY SUDDENLY WANTS TO TALK ABOUT COMPLIANCE.
— SNW | SHS – HUMAN FIRST
16 November 2026
Oh, humanity.
The things people do for money.
And, perhaps even more revealing, the things people suddenly become incapable of doing when money is involved.
Seeing. Questioning. Investigating. Intervening. Taking responsibility.
Sometimes it’s not even what you do that exposes your priorities.
It’s what you conveniently fail to do.
Now look at Revolut.
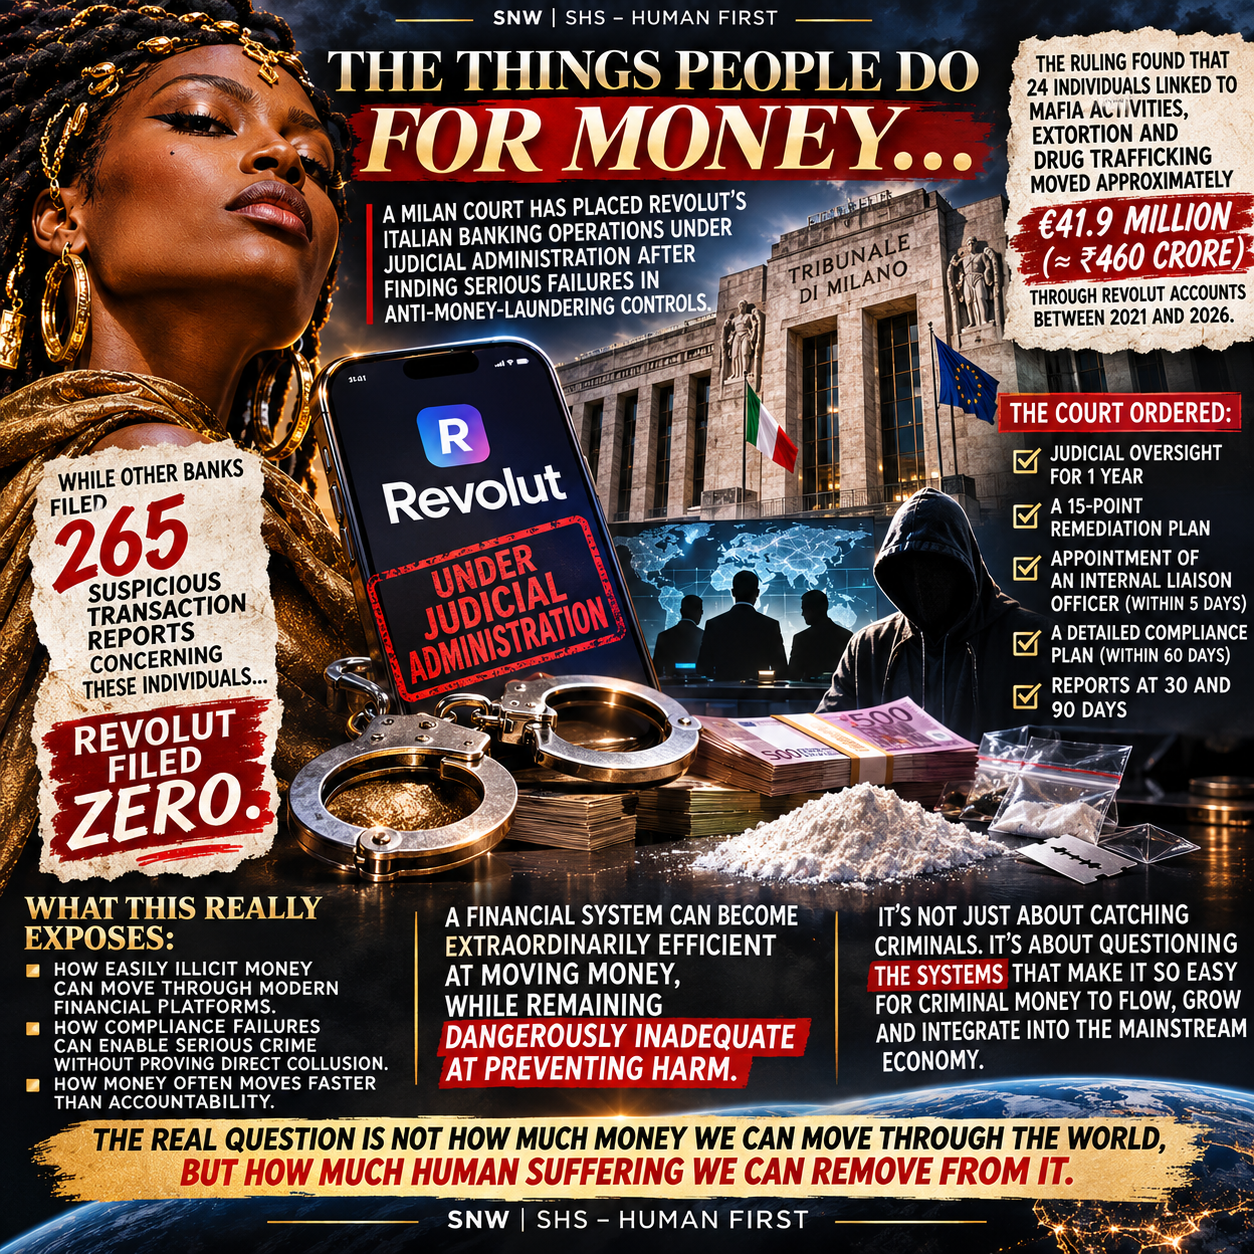
An Italian court has placed its Italian banking operations under judicial administration for a year following findings of serious anti-money-laundering control failures.
According to the ruling, 24 individuals under investigation or previously convicted in various criminal cases were able to conceal financial flows totalling approximately €41.9 million between 2021 and 2026.
And here’s my favourite part.
Other banks reportedly filed 265 suspicious-transaction reports involving these individuals.
Revolut?
ZERO.
Not one.
Now, I’m not saying that proves the bank knowingly collaborated with criminals. It doesn’t. The company isn’t under criminal investigation, and the judicial intervention is corrective rather than a criminal conviction.
But that’s precisely why I find the case so interesting.
YOU DON’T NEED TO INTEND TO FACILITATE HARM FOR YOUR FAILURES TO BECOME PART OF THE MACHINERY THAT ENABLES IT.
And perhaps that’s one of the most important things we need to understand about the organisation of society.
We spend so much time asking whether somebody deliberately committed wrongdoing that we sometimes forget to investigate the systems that made wrongdoing possible.
Because apparently, if you didn’t personally commit the crime, there’s an entire conversation to be had about how much responsibility you should carry for enabling its continuity.
How convenient.
THE MONEY WAS MOVING. BUT WHERE WAS THE RESPONSIBILITY?
Let’s look beyond the bank for a moment.
Money laundering is not simply dirty money being washed clean through a financial institution.
It’s a process through which the proceeds of criminal activity are concealed, disguised or integrated into apparently legitimate economic activity.
And what sits behind those proceeds?
Potentially extortion.
Drug trafficking.
Fraud.
Exploitation.
Threats.
People whose lives have been affected by the activities that generated that money.
The human consequences don’t magically disappear because the money enters a beautifully designed banking application.
THE MONEY DOESN’T BECOME INNOCENT BECAUSE ITS TRANSACTION HAS A RECEIPT.
And yet, isn’t that how we’ve organised so much of society?
Follow the numbers.
Count the revenue.
Measure the growth.
Celebrate the expansion.
And then, when someone discovers that the mechanisms supposed to protect society weren’t working, we begin talking about control frameworks, remediation plans, regulatory supervision and institutional reform.
All perfectly necessary.
But why did those protections fail in the first place?
What was missed?
Who was responsible for identifying it?
Who had the information?
Who had the authority to intervene?
And what organisational priorities allowed the deficiencies to persist?
Those are the questions that matter.
Not because we’ve already established intentional corruption.
But because a failure to prevent foreseeable harm deserves investigation even when intentional wrongdoing cannot be established.
THE CORPORATE COLONIST HAS AN INTERESTING LITTLE RELATIVE: INSTITUTIONAL NEGLECT.
I was just writing about the modern-day corporate coloniser.
Acquire. Consolidate. Leverage. Expand. Repeat.
And now look at another side of the financial world.
Transactions. Accounts. Deposits. Transfers. Growth.
A rather extraordinary infrastructure built to move money around the planet.
We’ve developed sophisticated financial technology capable of transferring funds across borders in seconds.
But technological sophistication doesn’t automatically produce ethical sophistication.
A financial system can become extraordinarily efficient at moving money while remaining dangerously inadequate at identifying the harm associated with it.
And isn’t that fascinating?
WE CAN BUILD THE TECHNOLOGY TO MOVE MILLIONS, BUT STILL FAIL TO ORGANISE THE RESPONSIBILITY THAT SHOULD FOLLOW THOSE MILLIONS.
We know how to build financial empires.
We know how to attract investors.
We know how to expand internationally.
We know how to create interfaces so attractive that people can barely resist signing up.
But ask whether every organisation has developed equally sophisticated systems of accountability, and suddenly we’re discovering some rather uncomfortable gaps.
I wonder how many of those gaps would receive more urgent attention if their consequences appeared directly on the company’s balance sheet.
Because that’s what money does to priorities.
It gives organisations a language in which certain things become extremely important while others can become remarkably easy to overlook.
And unless institutions are deliberately organised to prevent it, financial performance can overshadow the human consequences of operational decisions.
MONEY IS THE THIRD WORLD WAR. AND THE BATTLEFIELD IS STILL YOUR MIND.
I’ve said it before.
Money is the Third World War.
Not because every financial transaction is an act of violence, but because humanity has allowed access to money to determine an extraordinary proportion of its survival, opportunities, relationships, decisions and institutional priorities.
And now look at what that dependence produces.
People commit crimes to obtain money.
Others develop systems to conceal the proceeds.
Others become intermediaries in moving it.
Others fail to recognise the warning signs.
And society eventually pays for the investigations, enforcement, prosecutions and consequences.
We create entire economies around managing the damage caused by behaviour that was motivated, enabled or rewarded through money.
AND THEN WE CALL THE FINANCIAL SYSTEM A MEASURE OF OUR DEVELOPMENT.
Development towards what, exactly?
Towards a society in which we have more sophisticated mechanisms for moving the proceeds of harm than for preventing harm from occurring?
Towards a world where the cost of investigating misconduct becomes yet another industry?
Where human suffering generates employment, contracts, consultancy fees, legal expenses and entire professional sectors dedicated to managing the aftermath?
Of course we need investigators, lawyers, regulators and financial-crime specialists while these problems exist.
But I would much rather live in a society whose success was measured by how effectively it reduced the need for all that remedial work.
PREVENTION IS A GREATER ACHIEVEMENT THAN PROFITING FROM THE MANAGEMENT OF CONSEQUENCES.
And there it is again.
The difference between organising society for continuity and organising society around the opportunities generated by its dysfunction.
FIFTEEN POINTS TO CORRECT WHAT SHOULD HAVE BEEN WORKING.
According to the reporting, Revolut must now implement a 15-point remediation plan under court supervision.
Fifteen points.
Two judicial administrators.
Reviews of compliance procedures, transaction monitoring and customer controls.
And Revolut says it will cooperate fully with the authorities.
Good.
Correct what needs correcting.
But I want us to examine the larger lesson.
If a financial institution requires judicial intervention to establish adequate protections, the investigation shouldn’t end with whether the new procedures are eventually implemented.
It should extend to understanding the conditions that allowed the original deficiencies to exist.
Because paperwork isn’t accountability.
A compliance document is not the same thing as an operational culture of responsibility.
And a correction today does not automatically undo the consequences of yesterday.
IF AN ORGANISATION ONLY BECOMES ACCOUNTABLE AFTER ITS FAILURES ARE EXPOSED, WE MUST ASK WHAT WAS GOVERNING ITS DECISIONS BEFORE THE EXPOSURE.
Not presume the answer.
Investigate it.
Thoroughly.
That is the difference between seeking a culprit and examining a system.
AND THIS IS WHY I WANT MONEY OUT OF THE CENTRE OF HUMAN EXISTENCE.
Because I am tired of seeing humanity organise extraordinary intelligence around managing money while leaving fundamental human needs and responsibilities insufficiently addressed.
Tired of seeing institutions congratulated for their financial achievements before anyone has examined what those achievements actually contribute to the continuity of life.
Tired of watching society celebrate wealth as power while struggling to distinguish between somebody who creates value and somebody who merely accumulates it.
I don’t want a world where ethical behaviour depends on whether people can afford to practise it.
I don’t want people driven into exploitation, criminality or dependency because their opportunities for legitimate survival have been restricted.
And I certainly don’t want financial institutions to become so central to society that their operational failures can affect thousands or millions of people while responsibility becomes increasingly difficult to locate.
I want an organisation of society in which the protection of human life is not subordinate to the protection of financial performance.
And that’s why my ambition isn’t to become the wealthiest participant in the existing system.
It’s to develop something that makes the existing dependency on money unnecessary.
A society in which we examine what humans need, what the Earth provides, what we can create, and how those resources can be organised responsibly.
Where the ability to acquire doesn’t determine the right to exist.
Where financial influence isn’t mistaken for superior character.
Where accountability doesn’t begin only after damage has become expensive enough to attract attention.
And where people have reasons to contribute to society beyond the financial rewards they can extract from it.
That doesn’t mean criminality magically disappears.
It means we stop treating financial incentives as though they’re an adequate substitute for human responsibility.
THE GOAL ISN’T SIMPLY TO CATCH MORE CRIMINALS. IT’S TO BUILD A SOCIETY THAT PRODUCES FEWER REASONS, OPPORTUNITIES AND SYSTEMIC CONDITIONS FOR CRIMINALITY TO FLOURISH.
And we do that through organisation.
Education.
Provisioning.
Accountability.
Prevention.
Human development.
Actual investigation.
Not just another technological product marketed as progress.
And certainly not another billion-dollar institution expecting the public to confuse its financial success with the quality of its contribution to humanity.
The things people do for money.
The things they overlook.
The things they tolerate.
The things they justify.
And the extraordinary lengths society will go to protect the financial structures upon which it has made itself dependent.
I WONDER WHAT HUMANITY WOULD ACCOMPLISH IF IT APPLIED THE SAME INTELLIGENCE TO PROTECTING LIFE AS IT DOES TO MOVING MONEY.
Because money has never been the most intelligent thing humanity created.
The human mind created money.
And the human mind can create something better.
THE REAL QUESTION IS NOT HOW MUCH MONEY WE CAN MOVE THROUGH THE WORLD.
IT’S HOW MUCH HUMAN SUFFERING WE CAN REMOVE FROM IT.
And if you need a financial incentive to find that worthwhile, darling, you’ve just demonstrated precisely what needs changing.
— SNW | SHS – HUMAN FIRST
Case reference: Milan Court, judicial administration of Revolut Bank UAB’s Italian operations, reported 16 November 2026. The proceedings concern failures in anti-money-laundering safeguards, not a finding that Revolut deliberately participated in the criminal activities of its customers.


Leave a Reply